A §1031 exchange when some partners want cash and others want to reinvest.
One partner wants cash from a real estate sale. The others want to reinvest through a section 1031 exchange. Taking the cash inside the partnership can leave all of them with taxable gain.
Compare ownership and exchange alternatives before the sale is committed. A last-minute change in title does not guarantee the intended result.
This Daily Tax Planning Strategy considers a partial drop-and-swap and the conditions that matter.
View original post on LinkedIn ↗
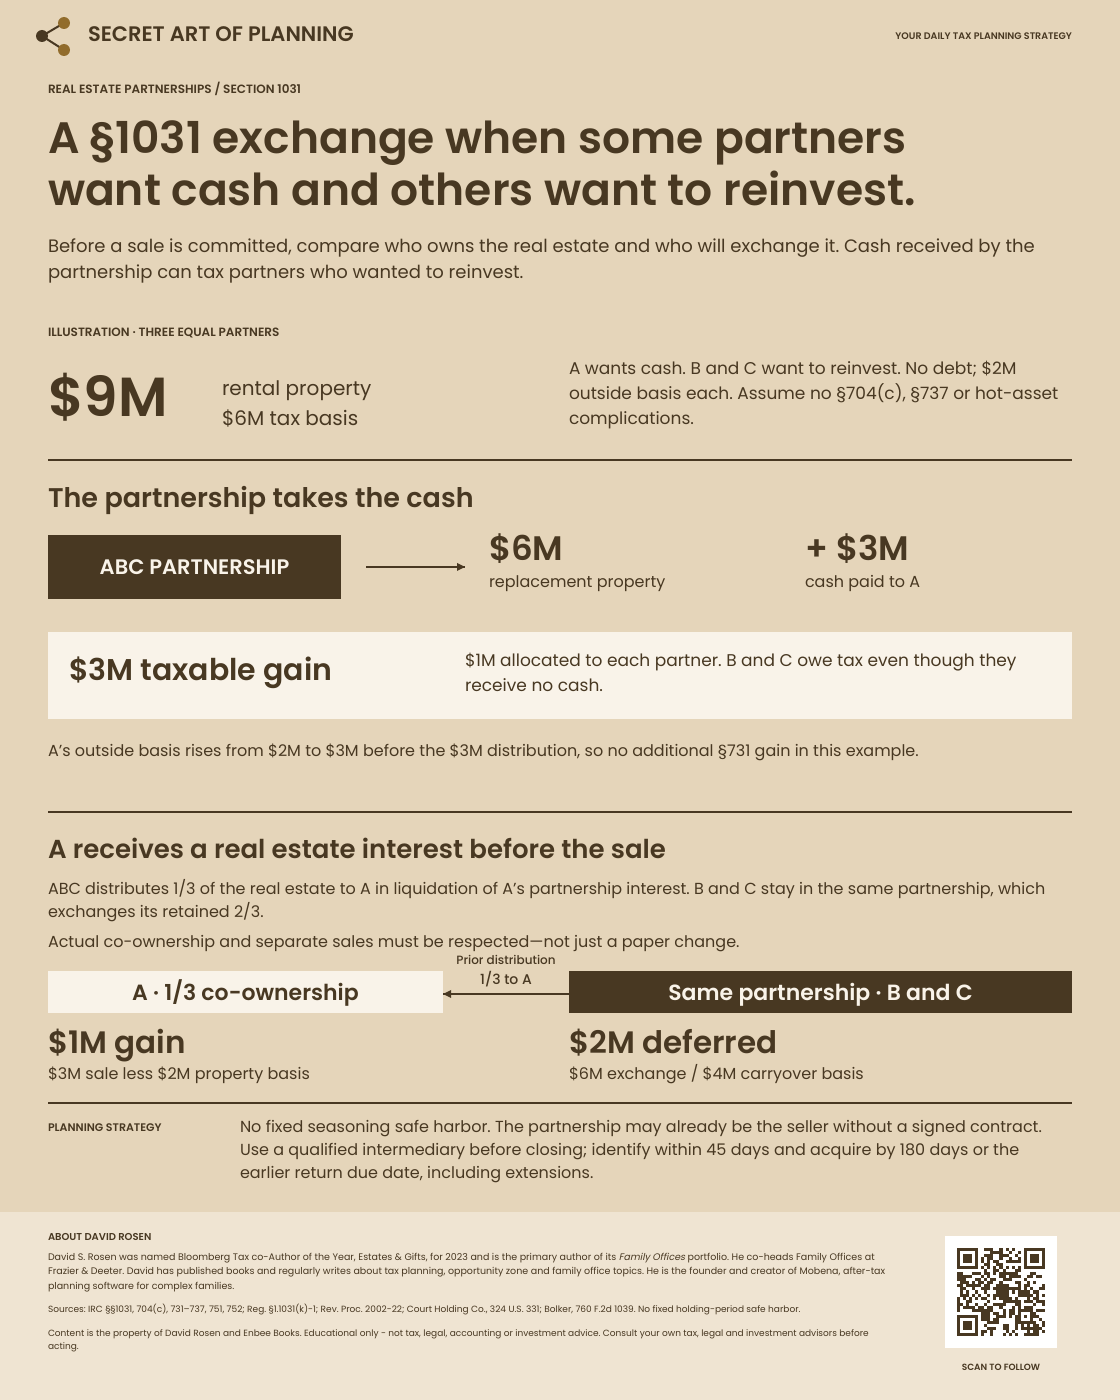
Graphic description
Ochre section 1031 partner-exit comparison. Three equal partners own $9M rental property with $6M basis, no debt and $2M outside basis each. If ABC exchanges for $6M property plus $3M cash paid to A, $3M gain is taxable, $1M to each partner, including cashless B and C. A's basis rises to $3M, avoiding additional distribution gain. In a conditional partial drop-and-swap, ABC distributes one-third of the real estate in liquidation of A's interest. A sells for $3M with $2M basis and $1M gain; the same continuing partnership with B and C retains two-thirds, exchanges $6M and defers $2M, retaining $4M basis. A leftward arrow labeled Prior distribution / 1/3 to A shows the real-estate distribution before A’s sale and the continuing partnership’s exchange. Actual co-ownership and separate sales must be respected, not just a paper change. Existing cautions cover no fixed seasoning safe harbor, qualified-intermediary planning and exchange deadlines. Includes sources, bio and QR.